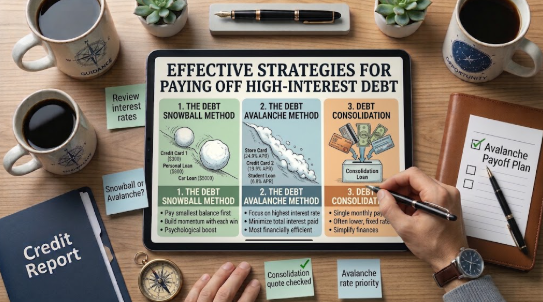
High-interest debt, particularly from credit cards or certain personal loans, can grow quickly because interest compounds on the remaining balance. Developing a clear payoff plan reduces total interest paid and shortens the time spent in debt.
List Every Debt
Begin by writing down each debt, the outstanding balance, the interest rate, and the minimum payment. Seeing the full picture makes prioritization possible and prevents overlooked accounts.
Two Popular Prioritization Methods
The avalanche method focuses on the debt with the highest interest rate first while making minimum payments on the others. Mathematically, this approach usually minimizes total interest paid.
The snowball method focuses on the smallest balance first. Paying off an entire account provides a psychological win that helps some people stay motivated. The choice between the two often depends on whether mathematical efficiency or behavioral momentum is more important for the individual.
Finding Extra Money for Debt Payments
Review the monthly budget for categories that can be temporarily reduced. Redirecting even modest amounts toward the targeted debt accelerates progress. One-time sources of cash such as tax refunds or bonuses can also be applied to principal.
Lowering the Interest Rate When Possible
Some borrowers successfully negotiate a lower rate with their current lender by explaining a solid payment history or the intention to transfer the balance elsewhere. Balance transfer credit cards with promotional low or zero percent rates can be useful tools if the remaining balance can be paid before the promotional period ends and if transfer fees are taken into account. Not everyone qualifies, and new credit applications affect credit scores.
Avoiding New Debt During the Process
Progress is undermined if new charges continue to accumulate on the same cards. Consider removing stored card information from online accounts and using cash or a debit card for everyday purchases until the high-interest balances are under control.
Seeking Additional Help
Nonprofit credit counseling agencies can help create debt management plans and may negotiate with creditors on behalf of clients. Be cautious of for-profit debt settlement companies that charge high fees and may damage credit.
Debt payoff strategies work differently for different people. This content is educational and not a substitute for personalized advice from a qualified professional.