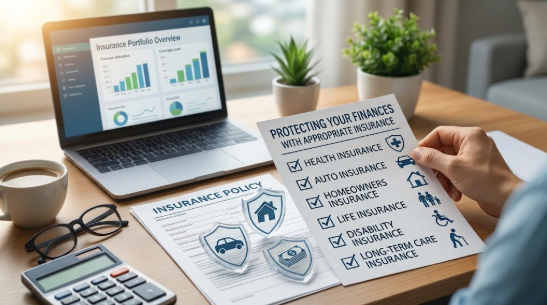
Insurance transfers the financial risk of certain events to an insurance company in exchange for premiums. Used thoughtfully, it protects against losses that would otherwise disrupt financial plans or create lasting hardship.
Health Insurance
Medical costs can be substantial. Health coverage reduces the risk that an illness or injury will lead to large out-of-pocket expenses or medical debt. Understanding deductibles, copayments, and network rules helps people use their coverage effectively.
Disability Insurance
Disability coverage replaces a portion of income if illness or injury prevents working for an extended period. Employer-provided coverage is common but may be limited in amount or duration. Individual policies can supplement workplace benefits. The definition of disability and the waiting period before benefits begin are important policy details.
Life Insurance
Life insurance provides a payment to named beneficiaries upon the death of the insured person. It is particularly relevant for those whose income supports dependents or who have co-signed debts. Term life insurance covers a specific period and is often more affordable for pure protection needs. Permanent policies combine a death benefit with a cash-value component and are more complex and expensive.
Property and Liability Coverage
Homeowners or renters insurance protects against damage to belongings and provides liability coverage if someone is injured on the property. Auto insurance is legally required in most places and covers damage and liability related to vehicle use. Umbrella liability policies can extend coverage beyond the limits of home and auto policies for those with higher exposure.
Evaluating Needs Periodically
Insurance needs change with life events such as marriage, home purchase, career changes, or the arrival of children. Reviewing coverage every few years or after major changes helps keep protection aligned with current circumstances. Comparing quotes from multiple reputable insurers can improve value, but the lowest premium is not always the best choice if coverage is inadequate or claims service is poor.
Insurance decisions involve trade-offs between cost and protection. This article is educational and does not recommend specific products or amounts of coverage. A licensed insurance professional or financial advisor can help evaluate individual situations.