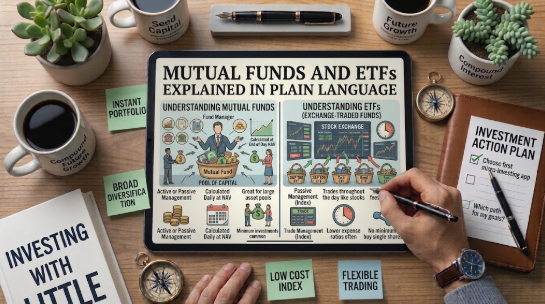
Mutual funds and exchange-traded funds (ETFs) both pool money from many investors to buy a diversified collection of stocks, bonds, or other assets. They offer a convenient way to gain broad market exposure without selecting individual securities. Understanding the main differences helps investors choose tools that fit their needs.
How Mutual Funds Work
When you invest in a mutual fund, you buy shares of the fund itself. The fund’s professional managers (or an index-tracking process) decide which securities to hold. Mutual fund shares are typically bought and sold once per day at the end-of-day net asset value (NAV). Some mutual funds are actively managed, meaning managers try to outperform a benchmark. Others are passively managed and aim to match an index.
How ETFs Work
ETFs also hold a basket of securities, but their shares trade on stock exchanges throughout the day, similar to individual stocks. Most ETFs are designed to track an index. Because they trade continuously, the market price can differ slightly from the underlying NAV, though the difference is usually small for widely traded funds.
Costs and Fees
Both structures charge an annual expense ratio that covers management and operating costs. Expense ratios for index-tracking funds are often very low. Actively managed mutual funds typically have higher expense ratios. ETFs may also involve brokerage commissions when bought or sold, although many brokers now offer commission-free ETF trades. Mutual funds sometimes carry sales loads or transaction fees, depending on the share class and broker.
Tax Considerations
ETFs are often structured in a way that can result in fewer capital gains distributions to shareholders compared with traditional mutual funds. This can be an advantage in taxable accounts. In tax-advantaged accounts such as retirement plans, the difference is usually less important.
Choosing Between Them
Investors who prefer trading throughout the day or who want the potential tax efficiency of ETFs may lean toward that structure. Those who value automatic investment plans or who are investing inside certain retirement accounts where mutual funds are the primary option may find mutual funds more convenient. Many investors use both.
Neither structure eliminates investment risk. Fund values fluctuate and investors can lose money. This article provides general educational information only and is not investment advice.